Turkey offers international business groups an opportunity to centralize certain management, financial, technical and operational support functions through a structure known as a Qualified Service Center (QSC). Designed for qualifying companies serving affiliated entities abroad, this model can be particularly relevant to multinational groups seeking to consolidate business services, coordinate regional operations and benefit from specific tax incentives.
A Qualified Service Center in Turkey may support functions such as financial reporting, accounting coordination, human resources, technology consulting, strategic management and technical support for related companies operating in different countries.
The framework introduced under Turkey’s Foreign Direct Investment Law establishes specific eligibility criteria and defines the activities that may be carried out within this structure. Qualifying centers may also benefit from corporate tax deductions and income tax exemptions for eligible employees, subject to the applicable conditions.
However, establishing a Turkish company alone does not automatically provide access to these incentives. Investors must evaluate the group’s international presence, the nature of the services provided, revenue composition, employee qualifications and ongoing compliance obligations.
This guide explains how the Qualified Service Center model works, which international groups may qualify, the principal tax advantages and the practical steps involved in establishing and operating a center in Turkey.
A Qualified Service Center in Turkey is a Turkish company providing management and support services to affiliated companies operating in at least three countries. To qualify, at least 80% of its annual service revenue must come from foreign group companies. Eligible centers can benefit from corporate tax deductions and employee income tax incentives, subject to legal requirements.
Turkey offers a tax incentive framework for international business groups seeking to establish regional management and shared service operations. Through the Qualified Service Center (QSC) model, eligible Turkish companies can provide financial management, accounting, consulting, human resources, technology and operational support services to affiliated companies abroad.
To qualify, the international group must operate in at least three countries, and the Turkish service center must derive at least 80% of its annual service revenue from foreign group companies.
Qualifying income from eligible cross-border services may benefit from corporate income tax deductions, subject to applicable legislation. Certain employees may also qualify for personal income tax exemptions on eligible salary components.
Establishing a Qualified Service Center in Turkey requires careful assessment of the group’s international structure, qualifying activities, revenue composition and ongoing tax compliance obligations.
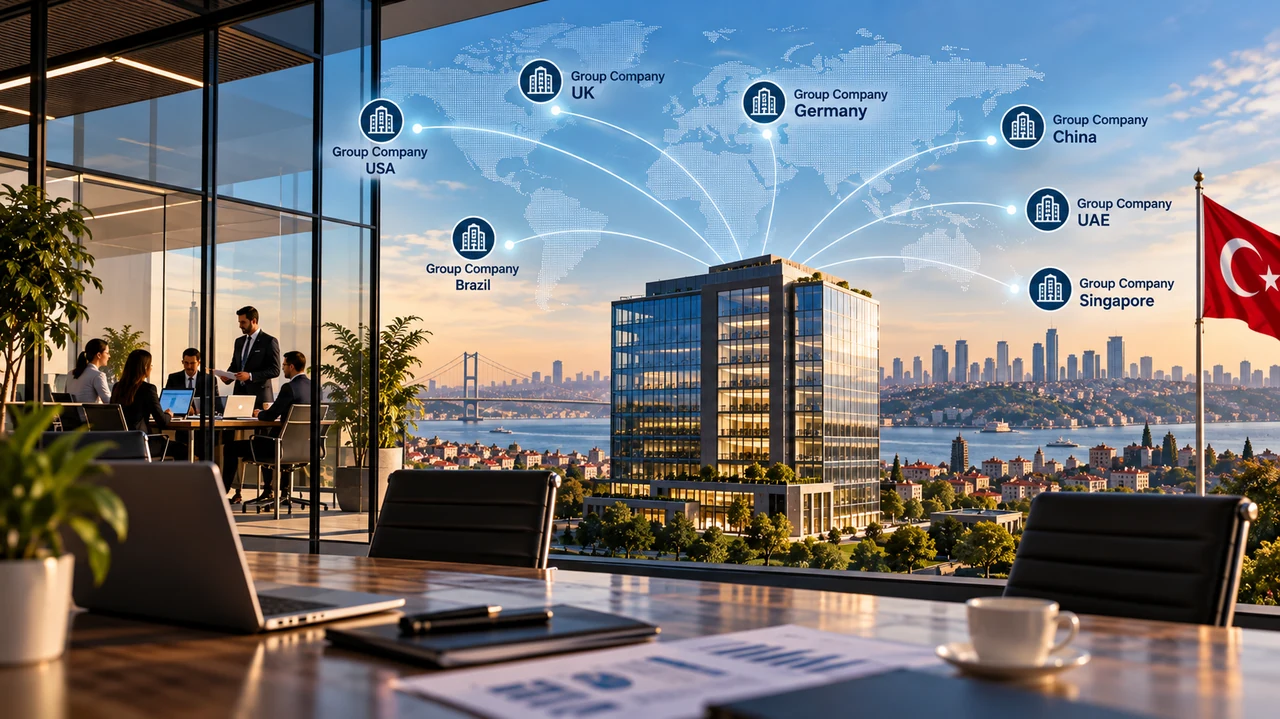
A Qualified Service Center is a Turkish capital company established to provide specified services to affiliated companies or a group of companies operating internationally, subject to the requirements set out in Turkey’s Foreign Direct Investment Law.
Unlike a company established primarily to sell products or services to independent customers in the Turkish domestic market, a Qualified Service Center focuses on providing eligible services to related companies located abroad.
The model is intended to encourage multinational groups to consolidate certain business functions in Turkey rather than maintaining separate teams in multiple jurisdictions.
Depending on the group’s operational structure, a Turkish service center may coordinate financial processes, provide management support, oversee human resources activities, assist with technology-related functions or organize technical and commercial support services for affiliated entities.
A typical structure involves a Turkish company employing qualified personnel who perform eligible services for related companies in other countries. The Turkish entity may charge those companies for the services provided, with the commercial arrangements documented through appropriate intercompany agreements.
For example, an international group operating in Germany, France and the United Arab Emirates may consider establishing a Turkish center to coordinate financial reporting, human resources administration and technology support for its foreign subsidiaries.
The Turkish company would need to perform activities permitted under the relevant legislation and satisfy the applicable eligibility requirements. Its contractual arrangements, service delivery model, revenue structure and transfer pricing policies should be consistent with its actual operations.
A Qualified Service Center should therefore be viewed as an operational service hub rather than simply a company registration or tax-planning arrangement.
Turkey may offer international groups several practical advantages:
Strategic location: Access to European, Middle Eastern and other regional markets.
Qualified workforce: Access to professionals in finance, accounting, technology, human resources and management.
International business environment: An established ecosystem of multinational companies and professional service providers.
Potential tax advantages: Specific corporate income tax deductions and employee income tax exemptions for qualifying operations.
Centralized operations: The ability to consolidate selected group functions within one operational structure.
The suitability of Turkey depends on the group’s activities, staffing requirements, international structure and ability to satisfy the applicable legal and tax conditions.
The Qualified Service Center framework is designed for international corporate groups that need to provide specified services to affiliated companies abroad.
It is particularly relevant to multinational businesses that want to centralize selected functions, improve operational consistency and establish a regional service hub.
Potentially relevant sectors include technology, manufacturing, financial services, e-commerce, professional services and international distribution. However, operating in one of these sectors does not, by itself, establish eligibility. The actual services and the group’s structure must be assessed against the legal criteria.
One of the central eligibility considerations is the international presence of the related corporate group. The statutory framework refers to active operations in at least three different countries.
Investors should therefore assess the group’s existing legal entities, actual business activities and relationships between the proposed Turkish center and its foreign affiliates before proceeding.
The presence of companies in several countries should not be treated as sufficient without examining whether the statutory conditions are met.
Another important criterion concerns the source of the Turkish company’s revenue. The framework specifies that at least 80% of annual revenue must be derived from related companies or the corporate group located abroad.
This requirement makes the revenue model a central part of the feasibility assessment. A company expecting to generate most of its income from unrelated Turkish customers may not fit the intended structure.
Before incorporation, investors should consider how services will be contracted, how fees will be calculated, which group entities will receive the services and how the resulting revenue will be documented.
Foreign investors should assess the appropriate Turkish company structure based on their operational needs, ownership arrangements and applicable legislation.
The proposed company must be established and operated in a manner consistent with the Qualified Service Center framework. Incorporation alone does not establish entitlement to the relevant incentives.
For information about the general establishment process, investors can consult our guide to company formation in Turkey.
No. The model is most relevant where a group has genuine cross-border service requirements, sufficient international operations and a business case for centralizing eligible activities in Turkey.
A company should evaluate the expected volume of services, staffing needs, revenue sources, intercompany arrangements and ongoing compliance costs before selecting this structure.
A preliminary eligibility assessment can help investors determine whether a Qualified Service Center is appropriate or whether another operating model would better meet their objectives.
A Qualified Service Center in Turkey can be established as either a Limited Liability Company (Ltd. Şti.) or a Joint Stock Company (A.Ş.), subject to the applicable legal and eligibility requirements.
Both company types can provide a legal framework for conducting business activities in Turkey. However, the most appropriate structure depends on the investor’s ownership arrangements, operational objectives, capital structure and long-term business plans.
A Joint Stock Company is often the preferred option for international corporate groups seeking to establish a Qualified Service Center because it offers a more formal corporate structure and may be better suited to larger-scale operations, complex ownership arrangements and long-term expansion plans.
Its corporate governance framework can also provide a familiar structure for multinational groups operating across multiple jurisdictions.
A Limited Liability Company may be suitable for investors seeking a more straightforward corporate structure. It can offer an appropriate framework for eligible service operations, depending on the group’s requirements and the applicable legislation.
Although both structures may be considered, a Joint Stock Company is often the preferred choice for a Qualified Service Center serving an international corporate group, particularly where a formal corporate structure and future expansion are important considerations.
Before making a decision, investors should evaluate the applicable capital requirements, management arrangements, shareholder structure and ongoing compliance obligations.
For a more detailed comparison, see our guides to Joint Stock Company in Turkey and Limited Liability Company in Turkey.
The activities performed by a Qualified Service Center are a fundamental part of the eligibility assessment. The applicable framework identifies specific categories of services that may be provided to related companies and corporate groups.
The following categories illustrate the principal functions that international groups may consider centralizing in Turkey. The precise scope of eligible activities should be checked against the applicable legislation and the center’s actual operating model.
A service center may perform or coordinate financial functions for affiliated companies, including:
Financial consulting and financial analysis.
Budgeting and financial reporting.
Cash and liquidity management.
Funding and borrowing coordination.
Investment and capital structure planning.
International accounting, compliance and audit-related functions.
These activities may help multinational groups standardize reporting processes, improve financial visibility and coordinate internal financial operations across jurisdictions.
The distinction between providing group-level support and performing regulated professional activities should be assessed where relevant.
International groups may centralize certain management and coordination functions in Turkey, including strategic management consulting, risk management and investment analysis.
A service center may assist group companies with planning, internal reporting, performance monitoring and coordination of management processes.
The actual services should be documented clearly so that the center’s activities can be distinguished from functions that fall outside the statutory scope.
Technology-related activities may include digital transformation consulting, technology consulting and data analysis, depending on the applicable statutory definitions.
For groups with operations in several markets, these functions may support the coordination of technology projects, data-driven decision-making and the standardization of internal processes.
Human resources services, training, promotion and brand management are among the activities identified in the legal framework.
A Turkish center may, for example, coordinate group-wide HR processes, organize employee training, support internal policies or assist with brand-related activities for affiliated companies.
Payroll administration and other employment-related processes should be structured in accordance with applicable Turkish labor, tax and social security requirements.
The framework also addresses coordination and management services relating to activities such as sales, after-sales support, technical support, research and development, external procurement, testing of newly developed products and laboratory services.
The inclusion of these categories does not mean every activity automatically qualifies. Investors should examine the precise service being delivered and distinguish between performing an eligible activity and merely providing general administrative support.
A detailed mapping of proposed activities to the statutory categories is therefore an important step before establishing the center.
One of the main reasons international groups consider establishing a Qualified Service Center in Turkey is the potential availability of specific tax incentives. These incentives are intended to encourage qualifying service activities, attract international business operations and support the development of Turkey as a regional service hub.
The applicable tax treatment depends on the nature of the services, the source of the revenue and whether the company satisfies the statutory conditions. Investors should therefore assess the proposed business model before relying on any anticipated tax benefit.
Qualified Service Centers may benefit from a special deduction applicable to qualifying income generated from eligible services provided to related companies abroad. The deduction is subject to the conditions established under Turkish tax legislation.
The relevant rules should be reviewed to determine which income qualifies, how the deduction is calculated and which supporting records must be maintained. Revenue from activities outside the eligible scope may receive different tax treatment.
Companies should also distinguish between a deduction from the corporate income tax base and an exemption from corporate income tax itself. The practical tax benefit depends on the applicable statutory mechanism and the company’s overall tax position.
The tax treatment of a Qualified Service Center is closely connected to the services it actually provides and the companies receiving those services. Intercompany agreements, invoices, service descriptions and evidence of work performed can help demonstrate the commercial substance of the arrangement.
The company should maintain records showing how its revenue relates to eligible activities and foreign group companies. Where necessary, separate accounting records or appropriate analytical classifications can help identify qualifying income.
Intercompany pricing should also reflect the nature of the services and comply with the applicable transfer pricing rules. The existence of a group relationship does not remove the need to support the commercial basis of charges between related entities.
The availability of a tax incentive should not be assumed solely because a company has been incorporated or describes itself as a Qualified Service Center.
Before applying a deduction or exemption, investors should confirm the current legislation, eligibility criteria, relevant revenue thresholds, documentation requirements and any additional conditions applicable to their circumstances.
For a broader overview of Turkish corporate taxation, see our guide to Corporate Income Tax in Turkey. The specific treatment of service income should be assessed separately against the rules applicable to Qualified Service Centers.
The treatment of employees is another important consideration when evaluating a Qualified Service Center in Turkey. Depending on the applicable conditions, qualifying employees may benefit from income tax exemptions associated with eligible services performed for foreign group companies.
For multinational groups, this aspect may influence staffing decisions, personnel costs and the location of regional support functions. However, employee-related incentives should be evaluated separately from the corporate tax treatment of the company.
Eligibility depends on the statutory criteria applicable to the employee, the work performed and the services provided by the center. The company should assess whether each relevant employee falls within the scope of the incentive rather than assuming that every employee automatically qualifies.
The employee’s role, professional responsibilities, relationship to the center’s eligible activities and the applicable legal requirements should be documented appropriately.
Even where an employee qualifies for an income tax exemption, the employer must continue to assess its payroll obligations under Turkish law.
These may include payroll calculations, withholding and declaration requirements, employment documentation and social security obligations. An income tax exemption should not automatically be interpreted as an exemption from social security contributions or every other employment-related liability.
Companies should establish payroll procedures that distinguish between eligible and non-eligible remuneration where required by the applicable rules. Supporting documentation should be retained to substantiate the treatment applied.
For practical assistance with employee administration, employers can review our HR and payroll services in Turkey.
Before transferring group functions to Turkey, an international business should prepare an employment cost assessment that considers salaries, employer social security costs, payroll administration and any available tax incentives.
The assessment should use the actual roles and compensation arrangements planned for the Turkish center. Any projected savings should remain conditional on the employees and the company meeting the relevant requirements.
Meeting the eligibility requirements is fundamental to establishing and maintaining a Qualified Service Center in Turkey. Investors should examine the group’s international structure, the center’s proposed activities, its revenue model and its ongoing operational arrangements before incorporation.
The requirements should be assessed as a connected framework. Satisfying one criterion does not necessarily compensate for failing another.
The relevant framework refers to international groups with active operations in at least three countries. Investors should examine the group entities and their activities to determine whether the statutory test is met.
A list of registered subsidiaries may not, by itself, establish that all relevant conditions are satisfied. The group should retain appropriate information about its international structure and operating activities.
The framework also refers to a requirement that at least 80% of the Qualified Service Center’s annual revenue comes from related companies abroad.
This criterion makes the center’s commercial model particularly important. The company should identify the expected recipients of its services, estimate the revenue attributable to each category and establish a process for monitoring the threshold throughout the relevant period.
The treatment of particular revenue items and the precise calculation method should be confirmed under the current legislation before the company relies on this requirement in its tax planning.
The services performed by the Turkish company must fall within the categories permitted under the applicable framework. The company’s registered business purpose, contracts, invoices, employee responsibilities and actual operations should be consistent with the activities for which the relevant treatment is claimed.
Investors should prepare a clear description of each proposed service and map it to the applicable statutory category. This process can also help identify activities that may require separate legal, regulatory or tax analysis.
Eligibility should be considered an ongoing compliance matter rather than a one-time incorporation decision. Changes in the group’s structure, service recipients, revenue composition or activities may affect the company’s position.
A practical compliance file may include:
Corporate group structure and information about foreign affiliated companies.
Intercompany service agreements and descriptions of the services provided.
Invoices and supporting records for service delivery.
Revenue analysis supporting the relevant eligibility criteria.
Employee records and documentation supporting any claimed employment-related incentives.
Accounting, tax and payroll records required under applicable legislation.
These records should be maintained in accordance with the applicable legal requirements and made available when needed to support the company’s tax treatment.
A preliminary review of the group’s structure and proposed operations can help identify potential eligibility issues before the company commits to establishment costs and staffing arrangements.
Establishing a Qualified Service Center in Turkey requires more than registering a company. International investors should evaluate the proposed activities, corporate structure, revenue model and operational requirements before beginning the incorporation process.
A structured approach can help investors identify potential eligibility issues early and prepare the documentation needed to operate the center.
The first step is to determine whether the international group and its proposed Turkish operations satisfy the applicable Qualified Service Center requirements.
This assessment should cover the group’s international presence, the services to be provided, expected revenue sources and the relationship between the Turkish company and its foreign affiliates. Investors should also identify which activities fall within the statutory scope of the regime.
A preliminary feasibility assessment can help establish whether the proposed structure is commercially viable and potentially eligible for the relevant incentives.
The appropriate legal structure should be selected according to the applicable legislation and the group’s operational requirements.
Investors should consider ownership arrangements, management responsibilities, share capital, the intended business activities and the company’s long-term operating model.
The incorporation process generally involves preparing the company’s articles of association, completing the required Trade Registry procedures and obtaining tax registration.
For further information, see our guide to company formation in Turkey.
Once the company structure has been determined, the incorporation documentation must be prepared and the required registration procedures completed.
Depending on the circumstances, these procedures may involve:
Preparing the articles of association and incorporation documents.
Registering the company with the relevant Trade Registry.
Obtaining tax registration and completing applicable tax-office procedures.
Establishing the company’s registered address.
Completing relevant electronic application and signature procedures.
Investors should also determine whether any specific authorization, notification or additional procedure applies to the proposed activities or location.
The company needs an appropriate registered address and operational arrangements consistent with its business activities and applicable requirements.
A virtual office may be an option in certain circumstances, but investors should confirm whether the proposed address and office arrangement are suitable for the intended operations and any relevant incentive conditions.
The company should also plan for opening a corporate bank account. Banks may request corporate documents, information about shareholders and directors, details of the business model and supporting information concerning the source of funds.
Account opening remains subject to the bank’s internal procedures and approval.
Before providing services to foreign group companies, the Turkish entity should establish appropriate contractual and operational arrangements.
Intercompany agreements should describe the services, responsibilities of the parties, pricing methodology and payment terms. The arrangements should reflect the services actually performed.
The company should also establish procedures for invoicing, accounting, revenue classification, employee administration and the retention of supporting documents.
After incorporation, the company must organize its accounting, tax reporting and employment processes in accordance with Turkish legislation.
The applicable procedures may include electronic invoicing and accounting systems, corporate tax compliance, payroll calculations, social security declarations and recordkeeping.
Investors should also implement a process for monitoring the conditions relevant to the Qualified Service Center regime. Changes in revenue composition, group structure or business activities may require a reassessment of eligibility.
A Qualified Service Center operating in Turkey must maintain appropriate accounting records and comply with the tax, employment and corporate reporting obligations applicable to its activities.
The availability of tax incentives does not eliminate ordinary compliance responsibilities. In practice, accurate documentation and consistent reporting are essential to supporting the company’s tax position.
The Turkish entity should maintain accounting records that accurately reflect its transactions and financial position.
For a Qualified Service Center, particular attention should be given to revenue earned from foreign group companies, intercompany transactions, operating expenses and income arising from activities outside the qualifying scope.
Where appropriate, analytical accounting procedures can help distinguish income associated with eligible services from other revenue. This can make it easier to support the tax treatment claimed in the corporate tax return.
Financial reporting should also be consistent with the company’s contractual arrangements and actual operations.
The company must assess its corporate tax obligations and determine how the applicable Qualified Service Center deduction should be calculated and reported.
The treatment of qualifying income should be distinguished from the treatment of non-qualifying income. Investors should also evaluate other tax obligations that may arise from their transactions, including value-added tax (VAT), withholding tax and other applicable liabilities.
The correct treatment depends on the nature of each transaction and the relevant statutory provisions.
For a broader overview of the applicable requirements, see our guides to Corporate Income Tax in Turkey and Annual Compliance Requirements in Turkey.
Transactions between a Turkish Qualified Service Center and foreign related companies should be documented and priced in accordance with applicable transfer pricing rules.
The company should retain evidence of the services performed, the commercial rationale for the charges and the methodology used to determine intercompany fees.
Service agreements, invoices, work records and relevant financial analyses may support the company’s position if the transactions are reviewed by the tax authorities.
Where the center employs personnel in Turkey, it must establish compliant payroll and employment procedures.
These may include employment contracts, payroll calculations, income tax withholding, applicable declarations, social security contributions and employee records.
Any income tax exemption available to qualifying personnel must be applied according to the relevant rules. Employers should not assume that an income tax exemption automatically removes other payroll or social security obligations.
The company should periodically review whether it continues to satisfy the requirements relevant to its Qualified Service Center status and tax incentives.
This review may include the group’s international operations, revenue composition, eligible service activities, employee qualifications and the supporting documentation maintained by the company.
A structured compliance calendar can help coordinate tax returns, financial reporting, payroll declarations and other statutory deadlines.
Turkey offers several tax and investment frameworks for businesses engaged in international services, technology activities and cross-border operations. Although some of these structures may appear similar, they have different purposes and eligibility requirements.
Investors should select a structure based on their actual business activities rather than assuming that all available incentives can be combined.
The Qualified Service Center regime and the general tax deduction available for certain exported services are separate mechanisms under Turkish tax legislation.
The service exporter framework applies to qualifying services provided to customers abroad, subject to its own statutory conditions. The Qualified Service Center regime is designed for companies meeting the specific criteria applicable to their international operations, eligible activities and revenue composition.
The two frameworks should therefore be evaluated separately. A company should not assume that satisfying the conditions of one regime automatically establishes eligibility for the other.
For further information about the broader service exporter framework, see our guide to Tax Exemption for Service Exporters in Turkey.
The Istanbul Financial Center (IFC) is a distinct location-based framework offering specific advantages to eligible participants.
Qualified Service Centers established within the IFC may benefit from a different incentive treatment where the relevant requirements, including applicable participant conditions, are satisfied.
The IFC may therefore be relevant to international groups considering a regional service hub in Turkey. However, investors should compare the location requirements, operating costs, applicable incentives and compliance conditions before deciding whether to establish their center within the IFC.
More information is available in our guide to the Istanbul Financial Center.
Free Zones in Turkey operate under a separate legal and incentive framework. The advantages available to a company depend on the nature of its activities, the applicable legislation and the conditions governing its operations within the relevant zone.
A Free Zone company and a Qualified Service Center should not be treated as interchangeable structures. The appropriate option depends on whether the business is primarily engaged in qualifying group services, export-oriented activities or other permitted operations.
Investors can explore the separate framework in our guide to Free Zones in Turkey.
Technology Development Zones (Technoparks), commonly referred to as Technoparks, are designed to support qualifying technology development and research and development activities.
Their incentive framework differs from the Qualified Service Center regime. A company should not assume that providing technology-related services to foreign group companies automatically qualifies it for Technopark incentives.
Businesses whose principal activities involve software development, research and development or other eligible technology activities may wish to assess the relevant requirements separately.
The choice between these structures should be based on the company’s actual activities, location, staffing requirements and eligibility for the relevant incentives.
The most suitable structure depends on the group’s commercial objectives, the nature of its services, its international operations and the legal conditions it can satisfy.
A comparison of the available frameworks should consider eligibility, location, tax treatment, operational costs, staffing requirements and ongoing compliance obligations before a final decision is made.
Establishing a Qualified Service Center in Turkey requires careful planning, from selecting the appropriate company structure to managing tax obligations and ongoing compliance. A&M Consulting Co. supports foreign investors and international corporate groups throughout the company establishment process and subsequent operations in Turkey.
Our services are designed to help international businesses coordinate their incorporation, accounting, taxation and employment-related requirements through a single professional service provider.
Company Formation in Turkey: Assistance with company incorporation, Trade Registry registration, tax registration and the coordination of establishment procedures.
Tax Consultancy: Guidance on Turkish tax legislation, corporate tax obligations and the assessment of applicable tax incentives.
Accounting and Financial Reporting: Bookkeeping, financial reporting, tax return preparation and ongoing accounting compliance.
HR and Payroll Services: Payroll calculations, employee administration, income tax withholding and social security compliance.
Ongoing Compliance Support: Assistance with recurring statutory obligations and the documentation required for the company’s operations.
Every international group has a different operational structure and set of requirements. We help investors identify the key considerations involved in establishing a Turkish company, assess their accounting and tax compliance needs, and coordinate the practical steps required to begin operations.
Where a Qualified Service Center incentive is being considered, the proposed activities, group structure and applicable statutory conditions should be assessed before the company relies on any anticipated tax benefit.
Planning to Establish a Qualified Service Center in Turkey?
Contact A&M Consulting Co. to discuss your project, understand the company formation process and identify the tax, accounting and payroll services your business may require.
A Qualified Service Center is a Turkish capital company established to provide designated management, financial, consulting, technology, HR and other support services to affiliated companies or corporate groups operating in at least three different countries. At least 80% of its annual revenue must come from foreign group companies.
Under Law No. 7582, eligible centers can benefit from a 95% deduction from the corporate tax base on qualifying foreign-source income, increased to 100% for eligible companies operating within the Istanbul Financial Center or designated industrial zones. These incentives are available for up to 20 accounting periods, subject to statutory conditions. Qualified personnel may also benefit from personal income tax exemptions on a portion of their salaries.
International corporate groups considering the centralization of management, financial, technical or other eligible services may assess this model. Eligibility depends on the group’s international operations, the activities performed, revenue sources and other statutory conditions.
Eligible companies may benefit from a special corporate income tax deduction, while qualifying employees may be eligible for income tax exemptions. The actual benefits depend on the applicable legislation and whether the relevant conditions are satisfied.
The framework is specifically associated with eligible services provided to related companies abroad. The applicable revenue threshold and the treatment of particular transactions should be confirmed under current legislation before the company begins operations.
Foreign investors can generally establish Turkish companies with full foreign ownership, subject to applicable legal requirements and any sector-specific restrictions. The proposed structure must also satisfy the separate requirements applicable to Qualified Service Centers.
The appropriate registered address and office arrangements depend on the company’s actual activities and the applicable requirements. Investors should assess whether their proposed office arrangement is suitable for their operations and any conditions attached to the incentives before choosing a virtual office or another address solution.
A Qualified Service Center must comply with the accounting, tax, payroll, social security and corporate reporting requirements applicable to its activities. It should also retain documentation supporting its eligibility and the tax treatment claimed.
A company’s eligibility may be affected if it no longer satisfies the relevant statutory conditions. Changes in international group operations, revenue composition, service activities or other qualifying criteria should therefore be monitored throughout the company’s operations.
The timeline depends on the incorporation procedures, document preparation, banking arrangements and any additional procedures relevant to the proposed activities. Investors should also allow time for assessing eligibility and organizing the operational documentation required for the intended structure.
A preliminary review is advisable because incorporation and eligibility for tax incentives are separate matters. Professional assessment can help identify potential issues relating to the group structure, eligible services, revenue requirements, intercompany arrangements and ongoing compliance.
Establishing a Qualified Service Center in Turkey can offer international corporate groups an opportunity to centralize eligible services and evaluate potential tax advantages. However, determining whether this structure is suitable for your business requires a careful assessment of your group’s international operations, planned activities, revenue model and applicable legal requirements.
Whether you are exploring the eligibility criteria, comparing different business structures or planning to establish your Turkish entity, obtaining professional guidance at an early stage can help you understand the requirements and prepare for the next steps.
At A&M Consulting Co., we work with foreign investors and international businesses seeking to establish and operate companies in Turkey. We can help you navigate the company formation process, understand your tax and accounting obligations, and organize the payroll and compliance arrangements required for your operations.
Not sure where to start? Contact our team to discuss your business objectives, the services you intend to provide to your affiliated companies and the practical considerations involved in setting up a Qualified Service Center in Turkey.
We will help you identify the key issues to assess and determine which professional services may be appropriate for your project.
Contact A&M Consulting Co. to discuss your plans and take the next step toward establishing your business in Turkey.
Abdullah Mercanlı is the Co-Founder of A&M Consulting Co. and has more than 20 years of professional experience in accounting, taxation, finance, payroll, and social security. He supports international businesses and foreign investors with tax compliance, company formation, and business operations in Turkey.
Registered member of ISMMMO · Registration No. 50555
WhatsApp Us